
Blogs
PW Consulting: Worldwide Aneurysm Coiling Market Poised to Reach USD 2.29 Billion by 2032, Growing at a 6.91% CAGR
By pmarketresearch, 2026-08-12
PW Consulting Releases Strategic Brief: Worldwide Aneurysm Coiling Market — Why 2026 Is the Pivotal Year for Commercial and Clinical Strategy
PW Consulting today publishes an executive briefing drawn from its forthcoming Worldwide Aneurysm Coiling Market report (base year 2025; historical 2020–2025; forecast 2026–2032). The brief synthesizes market-scale trajectories, regulatory and reimbursement inflections, and competitor movements that will materially influence program and portfolio choices in 2026. Our analysis shows a resilient expansion path — underpinned by product innovation, shifting procedure settings, and concentrated competitive dynamics — with the market growing from a 2025 baseline into a multi‑billion-dollar opportunity by the end of the forecast window at a compound annual growth rate (CAGR) of 6.91% (2026–2032). This announcement frames the strategic value of the full report for corporate leaders, investors, and health system strategists considering near-term investments, launches, or consolidation.
Industrial Inverted Microscopes Market
Why this briefing matters for 2026 decision-makers
- Time-to-market and regulatory positioning: 2026 will be a year when new device approvals and EU/US regulatory progress materially change competitive access. Companies that align clinical, regulatory, and commercialization plans now can capture premium access during limited windows following product launches.
- Reimbursement and hospital economics are tightening: Procedural and inpatient payments are significant determinants of adoption pace and site-of-care economics. Our report models how physician fee schedules and DRG reimbursement translate into hospital margin signals for coiling procedures and adjacent neurovascular solutions.
- Portfolio prioritization under concentration: The market is led by a relatively small set of entrenched neurovascular players. That concentration raises both barriers and opportunities: incumbent distribution networks and clinician relationships matter, but differentiated technology or compelling commercial propositions can accelerate share gains.
Market trajectory at a glance
PW Consulting’s device-level demand model quantifies a steady recovery and expansion from the 2020–2025 historical window into the 2026–2032 forecast period. After the 2025 baseline, the market is projected to expand at ~6.9% CAGR through 2032, reaching a substantially larger size by the end of the forecast horizon. This expansion reflects a mix of factors we quantify in the full report: population and procedure incidence trends, device mix evolution (detachable vs. bio‑active vs. coated solutions), pricing dynamics, replacement cycles, and the commercialization of new entrants.
Worldwide Screencast Software Market
What the PW Consulting report delivers — practical modules
- Independent market sizing and growth drivers: A transparent, device‑level model covering historical activity and a 2026–2032 forecast, with sensitivity analyses for incidence, pricing, and channel mix.
- Competitive landscaping and capability mapping: Detailed profiles of incumbent manufacturers, emergent entrants, and adjacent technology suppliers, with go‑to‑market posture, IP posture, and clinician adoption levers.
- Regulatory and reimbursement playbook: Actionable assessments of EU MDR impacts, US regulatory timelines, Medicare fee schedule implications for physicians, and inpatient DRG economics for hospitals.
- Commercial and pricing strategies: Scenario-based guidance for hospital contracting, distributor engagement, and site-of-care transition strategies between inpatient and ambulatory settings.
- M&A and partnership screening: Transaction-ready themes identifying biologics/technology pairings, geographic expansion priorities, and consolidation targets aligned with clinical differentiation.
- Clinical adoption pathways: Evidence generation roadmaps customized to product archetypes (framing vs finishing vs bioactive), incorporating trial designs, KOL engagement strategies, and registry approaches.
Key dynamics shaping vendor strategy in 2026
Several adjacent dynamics will determine who captures disproportionate value next year:
High-Density PCBs Market
- Regulatory momentum: Recent EU MDR certifications have enabled new commercial entries in Europe and prompted incumbents to accelerate post‑market commitments. Companies that finalize regulatory dossiers and align clinical claims with payers will shorten commercialization cycles.
- Reimbursement mechanics: PW Consulting’s reimbursement mapping highlights two practical benchmarks that influence margin: physician payment for the CPT-coded coiling procedure and hospital DRG payments for ruptured‑aneurysm admissions. These inputs materially affect provider willingness to adopt higher‑cost devices or to shift cases to ambulatory care settings where appropriate.
- Provider economics and site-of-care migration: Hospitals remain the predominant setting for complex aneurysm care, but ambulatory surgical centers and hybrid neurointerventional suites are growing as a function of throughput optimization and cost pressures. Commercial plans and suppliers must model differing adoption curves by site to appropriately price and support new products.
- Clinical differentiation and evidence: The fastest routes to adoption combine superior ease of use with robust clinical or real‑world outcomes. For certain product classes, surrogate endpoints and registry data will unlock hospital formulary inclusion faster than comparative randomized trials.
Competitive landscape — who to watch
The competitive field is anchored by multinational medical device companies and specialized neurovascular firms. Our competitive assessment focuses on capabilities, product families, distribution strength, and recent strategic moves that will matter to buyers in 2026.
- Medtronic (Dublin, Ireland) — A global incumbent offering a broad family of detachable coil solutions for endovascular embolization; strength lies in deep clinician relationships and integrated neurovascular portfolios.
- Stryker (Kalamazoo, MI, USA) — Competes with the Target family of detachable coils and leverages strong commercial channels in key markets.
- Terumo Neuro / MicroVention (Aliso Viejo, CA, USA) — Offers a full range of coil options and maintains technical breadth across platinum and specialty coil designs.
- Penumbra, Inc. (Alameda, CA, USA) — Markets an embolization system that pairs coils with adjunct technologies; integration of system components is a notable commercial differentiator.
- Johnson & Johnson MedTech — Cerenovus (New Jersey, USA) — Focuses on a family of coils spanning framing to finishing, supported by global neurosurgical sales forces.
- Regional and emerging players — Companies such as Kaneka (Japan/Europe launch), Balt Group (France), Phenox (Germany), MicroPort NeuroTech (China), and several U.S. and European specialists maintain focused portfolios, niche clinician relationships, and regional regulatory advantages.
- Disruptor watch: Neuravention (U.S.) — An early-stage innovator with plans for a 2026 FDA submission and potential commercial activity. If regulatory progress is realized, the company could become a strategic target for partnerships or acquisitions.
Notable recent developments underscore this dynamic: Kaneka’s i‑ED COIL secured EU MDR certification and launched commercially in Europe, demonstrating the speed at which an MDR‑cleared product can be monetized in core neurovascular markets. Separately, Neuravention’s planned FDA submission in early 2026 signals potential near‑term product evolution in the U.S. market that incumbents and investors should monitor closely.
How purchasers and investors should use the full report
PW Consulting designed the report as an operational tool, not just an academic exercise. Use cases include:
- Portfolio leaders: Reprioritize R&D and clinical investments against modeled adoption curves to optimize spend across framing vs finishing coil designs and next‑generation bioactive options.
- Commercial executives: Build pricing and contracting scenarios tied to hospital DRG economics and physician reimbursement, and construct a time‑phased launch playbook keyed to regulatory milestones.
- Business development and M&A teams: Screen targets against capability gaps, and size near‑term revenue uplift and integration effort for bolt‑on vs transformative deals.
- Health systems and payers: Anticipate supply‑side innovations and align internal protocols, procurement strategies, and site‑of‑care plans to maintain quality while managing cost-per-case.
- Private capital: Calibrate valuation assumptions to market growth, competitive concentration, and potential disruption from late‑stage entrants.
Methodology and confidence
PW Consulting’s projections combine device‑level demand modeling, primary interviews with clinicians and hospital procurement leads, regulatory timeline analysis, and payer reimbursement mapping. The report presents base, upside, and downside scenarios and includes sensitivity analyses for incidence rates, pricing trajectories, and substitution between device classes. Where granularity matters for commercial execution — e.g., hospital formulary thresholds, payer prior‑authorization drivers, or clinician training requirements — the full report offers actionable matrices and playbooks. Our confidence intervals and assumptions are documented to facilitate adaptation to company‑specific forecasts.
What we are deliberately withholding in this briefing
To preserve the report’s value as a transaction and strategy resource, we have intentionally omitted detailed regional and end‑user revenue splits, specific device‑class revenue breakdowns, and granular competitive share tables. These elements are key deliverables in the full report, and they are provided to paying subscribers to support confidential strategic planning, competitive benchmarking, and investment underwriting.
Next steps and how to access the full analysis
For executive teams preparing 2026 product launches, M&A pipelines, or commercial realignment, the full Worldwide Aneurysm Coiling Market report provides the granular intelligence needed to move from insight to action. PW Consulting offers tailored briefings that overlay your product portfolio or acquisition target on our model to produce transaction‑ready financials and a prioritized execution plan.
To request the complete report or to schedule a customized executive briefing, visit our report page or contact our industry practice leads. PW Consulting will run a limited number of confidential deep‑dive sessions in Q1 2026 to support clients preparing regulatory submissions, commercial launches, or strategic transactions in the aneurysm coiling space.
For detailed analysis of this topic, please visit the official page: Worldwide Aneurysm Coiling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Prescription Diet Pet Food Market to Reach USD 28,387.13 Million by 2032 at a 7.12% CAGR, with Top 3 Firms Holding 68.45%
By pmarketresearch, 2026-08-12
Worldwide Prescription Diet Pet Food Market: Strategic Imperative for 2026
PW Consulting today releases a targeted industry briefing derived from our comprehensive Worldwide Prescription Diet Pet Food Market report (base year 2025, forecast period 2026–2032). For executives planning 2026 initiatives, the market’s macro trajectory is clear: the global prescription diet segment reached USD 17,540.0 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 7.12% through 2032, with the base-case model pointing toward roughly USD 28.4 Billion by 2032. The next 12–18 months will determine which players consolidate leadership, which channel models win veterinarian endorsement, and which supply chains remain resilient under inflationary raw-material pressure.
Ceiling-mounted OT Light Market
Why 2026 Is a Pivotal Year
-
Accelerating patient-level demand: Demographics of pet ownership (aging companion animals, higher spend per household) and stronger clinical adoption of therapeutic nutrition are sustaining long-term volume growth. That underlying demand, combined with premiumization in developed markets, is driving above-average category expansion versus conventional pet food.
Wheelchair Scale with Armrests Market -
Channel dynamics are intensifying: Prescription diets are still primarily dispensed via veterinary channels. Regulatory clarity—especially FDA rules requiring veterinary authorization in the U.S., AAFCO nutritional standards, and EU registration requirements—means go-to-market strategies must embed compliance and clinician engagement from product conception through commercialization.
Worldwide Electric Scooter Batteries Market -
Cost and supply-chain stressors: Raw-material volatility is an immediate operational risk. For example, chicken meal prices rose materially year-over-year, reflecting disease and supply disruptions; producers that lock in diversified sources or implement hedging and formulation flexibility will protect margins.
-
Market concentration and competitive pressure: The top commercial groups hold a significant share of the prescription diet market, creating high barriers to entry for new national brands but opening white-space opportunities in niche therapeutic formulations, value channels, and services that complement veterinarian workflows.
What PW Consulting’s Report Delivers (Practical Deliverables)
-
Proprietary market model: Transparent annual revenue series (historical 2020–2025; forecasts 2026–2032) with scenario toggles for demand elasticity, raw-material inflation, and channel mix, enabling CFOs to stress-test P&L outcomes for 2026 planning cycles.
-
Commercial playbooks: Actionable frameworks for veterinary engagement, sample and trial programs, field force deployment, and pricing strategies tied to reimbursement behavior and clinic economics.
-
Regulatory and quality checklist: A stepwise compliance roadmap covering FDA/CVM expectations, AAFCO labeling requirements, FSMA preventive controls, and EU registration constraints—mapped to commercial launch milestones.
-
Supply-chain and procurement playbook: Sensitivity analyses for key commodity inputs, supplier-risk heatmaps, recommended hedging instruments, and a contract-manufacturing versus in-house decision matrix.
-
Competitive benchmarking and capability scorecards: Comparative assessment of clinical portfolio breadth, veterinary channel strength, evidence-generation capabilities, brand trust metrics, and manufacturing footprint—designed for M&A screening and alliance decisions.
-
Innovation and R&D prioritization guide: Clinical differentiation strategies (e.g., renal, dermatology, weight management, gastrointestinal), required evidence thresholds for veterinary adoption, and recommended trial designs to shorten time-to-recommendation.
-
Risk register and mitigating actions: Actionable mitigations for regulatory shifts, recall scenarios, ingredient shortages, and reimbursement changes—mapped to trigger points for executive decision-making.
Competitive Landscape: Strategic Takeaways
-
Incumbent leaders maintain scale advantages. Core global players have built portfolios that span multiple therapeutic areas and maintain exclusive veterinary distribution relationships. These firms combine clinical trial capacity, long-standing clinician trust, and extensive cold-chain and co-packing capabilities. Their ability to bundle clinical nutrition with practice-level services (training, diagnostics integration, loyalty programs) is a key defensive moat.
-
Recent product and portfolio moves signal incremental innovation rather than category disruption. Several leading firms refreshed renal and wet-formula offerings, broadened pack-size options, and showcased line updates at major industry expositions—moves that optimize shelf productivity and clinician convenience rather than rework channel economics.
-
Mid-sized specialist players are focusing on focused therapeutic niches and faster clinical evidence generation to gain clinician mindshare. These companies are attractive M&A targets for larger groups seeking to plug portfolio gaps without the integration friction of a full-scale R&D acquisition.
-
Concentration metrics: The market shows a high degree of top-tier concentration, reinforcing that strategic plays in 2026 should either align with incumbents (partnerships, co-branding, distribution alliances) or be laser-focused on under‑served therapeutic areas and service models.
Operational and Commercial Priorities for 2026
-
Vet-first commercialization: Invest in repeatable clinician engagement programs—clinical champions, continuing education, and evidence-sharing platforms—rather than broad consumer advertising for prescription categories.
-
Regulatory-first product development: Embed regulatory and labeling requirements into early-stage formulation decisions; failing to demonstrate conformance to AAFCO/FDA/EC expectations will delay launches and erode market window opportunities.
-
Hedged sourcing and formulation flexibility: Given recent commodity shocks (e.g., notable year-over-year increases in chicken meal pricing), companies should pursue multi-sourcing, flexible formulations, and locked-price procurement to stabilize gross margins.
-
SKU rationalization and portfolio economics: Prune low-throughput SKUs, optimize pack-size tiers that improve clinic inventory turnover, and align product formats (wet vs dry) with clinic dispensing economics.
-
Service and data monetization: Integrate nutrition plans into clinic practice management systems and telehealth modules to create recurring revenue streams and capture real-world adherence data—an emerging differentiator in clinician purchasing decisions.
Investment and M&A Lens
-
Target capabilities should include clinical-evidence pipelines, strong veterinary distribution contracts, and manufacturing scale for wet formulas. Buyers seeking near-term returns should prioritize targets that add defensible clinician relationships and cost-saving manufacturing synergies.
-
Joint ventures with veterinary networks and strategic minority stakes in diagnostic companies can accelerate route-to-recommendation by bundling therapeutic nutrition with point-of-care diagnostics.
-
Private-label and contract-manufacturing partnerships represent lower-capex routes to expand distribution footprint while mitigating supply-chain risk—an attractive play for regional players aiming to scale quickly.
How to Use This Report for 2026 Decision-Making
-
Board and investor briefings: Translate scenario outputs into funding requests, capex prioritization, or defensive measures (e.g., supplier contracts) required to protect 2026 margin targets.
-
Commercial launch planning: Use our evidence thresholds and clinician engagement playbooks to de-risk product launches and compress the time from launch to clinic adoption.
-
Procurement and manufacturing strategy: Apply the supply-chain sensitivity dashboard to set procurement policy, negotiate fixed-price contracts, and decide on internal manufacturing investments versus CMOs.
-
M&A screening: Leverage capability scorecards and concentration analysis to identify targets that deliver immediate clinical access or add differentiated therapeutic formulations.
PW Consulting’s briefing is intentionally crafted as a decision-ready executive summary. It demonstrates the analytical depth and practical orientation that senior teams need to act in 2026—while preserving the granular segmentation matrices, detailed regional and application splits, and downloadable datasets that underpin our models. Those datasets, including the full breakouts and interactive forecast model, are available in the full report and data annex on the PW Consulting report page.
To discuss tailored scenarios for your organization, license the full dataset, or arrange a bespoke advisory session to translate these findings into a 90‑day action plan, contact PW Consulting’s Strategic Insights team.
For detailed analysis of this topic, please visit the official page: Worldwide Prescription Diet Pet Food Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pearls Market Outlook — Asia Pacific Commands USD 1,873.6 Million Share, Underscoring Regional Dominance
By pmarketresearch, 2026-08-12
Pearls Market 2026 Preview: Strategic Playbook for Decision‑Makers — PW Consulting Releases Pearls Market (Base Year 2025) Intelligence Brief
Executive summary
PW Consulting today unveils the Pearls Market report (base year 2025), an action‑oriented market intelligence product designed to equip corporate strategists, retailers, supply‑chain leaders and investors with the insights required to make high‑stakes decisions in 2026. The global pearls market — valued at approximately USD 4,150 Million in 2025 — is poised for steady expansion through the forecast window (2026–2032), driven by a projected compound annual growth rate (CAGR) of 5.25%. Our analysis combines macro forecasting with practical playbooks on sourcing resilience, premiumization, sustainability compliance and channel economics.
Spironolactone Drugs Market
Why this report matters for 2026 planning
-
Timing: As market growth accelerates into the latter half of the decade, 2026 will be a pivot year for strategic repositioning — between value and luxury segments, between vertically integrated incumbents and nimble disruptors, and between traditional distribution and digital experiential commerce.
Network Monitoring Tools Market -
Policy & reputation risk: The industry is undergoing rapid institutionalization of standards and sustainability metrics. Recent sector initiatives and expanded classification guidance are reshaping provenance claims and consumer trust landscapes.
Reinforced Modified Polyethylene Market -
Fragmented supply structure: Measured concentration ratios indicate a distinctly fragmented industry structure, which creates opportunities for consolidation, niche differentiation and value chain capture.
Market trajectory — headline macros
Our bottom‑up model projects the market moving from a 2025 base of roughly USD 4.15 billion to an anticipated market size approaching USD 5.94 billion by 2032 under the central forecast path. That trajectory reflects a 5.25% CAGR across the 2026–2032 forecast window, with demand patterns shaped by premium jewelry purchases, evolving bridal and gifting cycles, and differentiated product narratives (provenance, sustainability, and rarity).
Key industry dynamics shaping 2026 decisions
-
Standards and science‑based sustainability: Institutional developments in 2025 — notably the launch of a global development community and the expansion of industry technical guides — are accelerating the adoption of standardized sustainability reporting and classification frameworks. For operators and brands, this raises the bar for traceability systems, eco‑labelling and consumer communication strategies.
-
Geopolitical and trade friction: Trade measures and tariff discussions affecting certain major producing regions create tangible supply and pricing volatility. Companies that proactively diversify procurement and build hedged inventory strategies will reduce margin erosion and maintain customer continuity.
-
Channel evolution: Luxury verticals continue to favor integrated product storytelling and provenance checks, while mid‑market channels are experimenting with compelling value propositions grounded in design rather than raw rarity. Digital‑first experiences and hybrid omnichannel models remain decisive battlegrounds for customer acquisition in 2026.
-
Fragmentation as strategic opportunity: With leading concentration metrics indicating a low degree of concentration among the top firms, scale plays and targeted consolidation remain high‑impact levers for those aiming to control premium supply or to access specialized farming networks.
Strategic implications for corporate decision‑makers
-
Supply chain resilience and sourcing playbooks: Build layered sourcing strategies that combine long‑term partnerships with high‑quality farms, contingency inventory buffers, and flexible procurement contracts. Invest in provenance technologies (e.g., blockchain anchoring, independent third‑party verification) to transform traceability into a commercial advantage.
-
Premiumization versus market expansion: Use a dual product architecture — a premium, provenance‑led line for luxury channels and a design‑ and value‑led line for broader audiences. Pricing architecture should reflect not just gem characteristics but storytelling and sustainability credentials.
-
Regulatory and standards readiness: Anticipate rising compliance costs related to expanded classification and disclosure requirements. Early alignment with newly published standards will reduce rework and accelerate market access, particularly in high‑value export markets.
-
M&A and partnership criteria: Target acquisitions that deliver either upstream security (controlled farming capacity) or downstream reach (retail and e‑commerce platforms). Given the fragmented market, bolt‑on deals and strategic JV structures remain more attractive than large scale roll‑ups in 2026.
-
Branding and consumer education investments: Allocate marketing spend to third‑party verification and narrative development — particularly on sustainability outcomes and farm‑to‑finger metrics that resonate with premium customers.
Competitive landscape — who matters and why
The pearls sector is characterized by a mix of century‑old luxury houses, family‑owned producers and large manufacturing clusters. PW Consulting’s competitive analysis synthesizes capability maps, ownership models and route‑to‑market strategies of the industry’s most consequential players:
-
Mikimoto (Tokyo, Japan) — an archetypal luxury house and early pioneer of cultured pearls. Its brand equity and product craftsmanship remain a benchmark for premium Akoya positioning; strategic action for challengers includes investing in signature design narratives and selective collaborations to erode heritage advantage.
-
Tasaki (Kobe, Japan) — a vertically integrated luxury jeweler controlling stages from farming to final design. Tasaki’s full‑stack model highlights the commercial value of upstream integration for quality control and margin capture.
-
Paspaley (Darwin, Australia) — a family‑owned leader in Australian South Sea pearls emphasizing sustainable, high‑quality farming. Its model spotlights sustainability as a premium differentiator and a protective moat in luxury channels.
-
Jewelmer (Makati, Philippines) — specializes in golden South Sea pearls with integrated cultivation and high jewelry development. Jewelmer’s positioning underlines the commercial potential of color‑led niche specializations and storytelling rooted in a single provenance.
-
Atlas Pearls (Subiaco, Australia) — a major producer and distributor demonstrating scale in white and silver South Sea categories; its distribution footprint is illustrative for companies focused on B2B wholesale expansion into global jewelry supply chains.
-
Chow Tai Fook (Hong Kong) — a dominant regional retailer with strong market access across Asia. The firm exemplifies how retail reach and promotional velocity can influence demand patterns at scale.
-
Zhejiang Grace Pearl Jewelry Co., Ltd (Zhuji, China) — emblematic of the freshwater production and manufacturing cluster, where manufacturing scale and verticalized supply chains drive affordability and rapid product iteration.
Across the competitive set, winners in 2026 will be those who combine provenance credibility, supply security and consumer platform mastery. The report profiles each firm’s strategic assets and offers comparator benchmarks for performance and positioning.
Recent sector developments — what changed in 2025 and why it matters
-
Industry initiative launch: The formation of a Global Pearl Development Community in late 2025 is a structural shift toward coordinated sustainability, standards and innovation across saltwater and freshwater sectors. Companies engaged early will influence standards and gain reputational credit.
-
Expanded technical guidance: The expanded industry classification guide introduced in 2025 elevates the rigor of producer claims. This has downstream consequences for labeling, retail disclosure and cross‑border trade approvals.
-
Market reporting and scientific monitoring: Updated sector reports and scientific monitoring initiatives strengthen the evidentiary basis for provenance and environmental claims — useful for premiumization and risk mitigation strategies.
-
Trade policy noise: Ongoing tariff discussions affecting certain sourcing channels introduce cost and lead‑time uncertainties. Scenario planning for alternative sourcing and pricing pass‑through will be essential for margin protection.
What the Pearls Market report contains — practical deliverables
PW Consulting’s Pearls Market report is structured to be operationally useful. Key deliverables include:
-
Market sizing and seven‑year forecasts (2026–2032) with scenario variations and sensitivity analysis.
-
Industry structure and concentration diagnostics, including CR3/CR5 analysis and implications for consolidation strategy.
-
Competitive intelligence dossiers for leading producers, retailers and manufacturer clusters, with capability matrices and strategic options.
-
Actionable go‑to‑market playbooks for premiumization, volume expansion, omnichannel distribution and licensed partnerships.
-
Supply‑chain resilience frameworks, procurement templates and a decision toolkit for inventory hedging and diversification.
-
Regulatory and standards readiness checklists aligned to the latest industry guidance and sustainability reporting expectations.
-
M&A target screening criteria and valuation heuristics tailored to the fragmentary structure of the industry.
Methodology and credibility
The report synthesizes primary interviews with producers, dealers and retailers; trade data; on‑site farm and manufacturing visits conducted during the 2020–2025 historical window; and a proprietary forecasting model calibrated to observed demand cycles and price elasticity patterns. Our approach balances quantitative rigor with qualitative industry knowledge to deliver prescriptive recommendations rather than abstract forecasts.
How to use this intelligence in 2026
-
Board-level strategy: Use the sizing, scenarios and concentration diagnostics to validate inorganic growth options, capital allocation and risk appetite.
-
Commercial leadership: Deploy the pricing and channel playbooks to optimize assortment and promotional calendars aligned to proven consumer triggers.
-
Supply‑chain teams: Implement the procurement templates and traceability frameworks to protect margins and satisfy evolving regulatory disclosure requirements.
-
Investors and acquirers: Leverage the M&A screening and valuation heuristics to prioritize targets that offer upstream security or downstream market access.
Call to action
PW Consulting’s Pearls Market report provides the strategic scaffolding required to act decisively in 2026. The document demonstrates the evidence base and the tactical playbooks; to access the granular segment tables, regional breakdowns, and downloadable data appendices that underpin our conclusions, please visit the full report page.
For detailed analysis of this topic, please visit the official page: Pearls Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Portable Gaming Consoles Market Reaches USD 16.5 Billion in 2025, Set to Expand at 8.98% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Portable Gaming Consoles Market 2026: Strategic Imperatives from PW Consulting
As portable gaming consoles transition from niche enthusiast gadgets to a mainstream pillar of interactive entertainment, 2026 will be a watershed year for strategic decision‑makers. PW Consulting’s latest market study—anchored on a 2025 base year and projecting through 2032—maps the structural shifts, technology inflection points, and competitive dynamics that will determine winners and laggards in the years ahead. This press release highlights the report’s strategic value for corporate leaders and institutional investors while preserving the granular segment-level intelligence for subscribers.
Worldwide Magnesium Hydroxide Fire Retardant Additives Market
Executive snapshot: scale, pace and market structure
The portable gaming consoles market has more than doubled in five years, expanding from roughly USD 8.45 billion in 2020 to USD 16.5 billion in 2025. PW Consulting projects continued expansion across the 2026–2032 forecast window at a compound annual growth rate of approximately 8.98%, with the total market approaching the low‑30 billions (USD) by the end of the period. These topline dynamics are underpinned by ongoing product innovation—hybrid handheld/home forms, Windows‑based portable PCs, cloud‑first handhelds, and foldable/expandable displays—paired with accelerating consumer uptake in both core and adjacent gamer cohorts.
Worldwide Brake Relining Service Market
Market concentration remains high: the top three manufacturers account for the bulk of industry value, and the top five intensify that dominance. Such concentration creates both barriers and opportunities: incumbent IP and service ecosystems can sustain premium pricing and margins, while agile entrants can capture niche share through price, design differentiation, or platform partnerships.
Worldwide Application Protection Market
Why this study matters for 2026 corporate decisions
- Investment prioritization — The report converts macro momentum into actionable capital allocation guidance by linking device adoption curves to likely revenue trajectories for first‑party software, hardware upgrades, and subscription services.
- Supply chain strategy — We quantify the sensitivity of device economics to component cost drivers—including advanced DRAM, OLED/POLED displays, and semiconductor availability—and offer mitigation pathways (dual sourcing, strategic inventory, long‑term contracts, and co‑development agreements).
- Platform and content roadmaps — For platform owners and first‑party studios, the study models trade‑offs between backward compatibility, cloud streaming, and native performance to inform 18–36 month content investment plans.
- M&A and partnership scouting — Subscribers gain a prioritized target list and a clash‑tested integration playbook to accelerate time‑to‑market for complementary hardware, middleware, or cloud service assets.
Report deliverables: practical tools inside
PW Consulting’s report is structured for immediate operational use by corporate strategy, product, and supply chain teams. Key deliverables include:
- Top‑line market forecasts and scenario analyses (base, constrained supply, and aggressive adoption) calibrated to 2025 baseline demand.
- Component cost sensitivity models linking semiconductor, DRAM, and display pricing to device BOM and margin outcomes.
- Risk maps covering regulatory compliance (battery safety and energy efficiency), geopolitics (export controls), and raw material exposure.
- Commercial go‑to‑market playbooks for OEMs, platform holders, and retail channels covering pricing, bundling, and service monetization.
- Competitive positioning matrices, strategic fit assessments, and M&A diligence checklists.
To preserve commercial value for stakeholders, the report deliberately withholds granular regional and application‑level revenue splits in this release; subscribers can access the full segmentation datasets and downloadable models on PW Consulting’s report portal.
Competitive landscape: what the leaders are doing
The portable gaming ecosystem in 2026 is defined by a coexistence of distinct value chains: proprietary hybrid consoles with deep first‑party libraries, PC‑centric handhelds optimized for AAA titles, cloud‑native devices targeting lower upfront cost, and a broad long‑tail of retro/enthusiast hardware. Key strategic moves by industry participants illustrate divergent but complementary plays:
- Nintendo Co., Ltd. — Building on legacy strengths, Nintendo’s hybrid device released in mid‑2025 reinforces the company’s dominance through backward compatibility and an entrenched first‑party software catalog. Strategic takeaways: Nintendo’s moat remains content and user experience; competitors will need unique value propositions (performance, cross‑platform integration) to peel off core gamers.
- Valve Corporation — Valve’s Steam Deck design philosophy prioritizes open PC access and modder friendliness. Ongoing development of a next‑generation model highlights the technical trade‑offs between silicon upgrades and battery life. Strategic takeaway: Valve plays to ecosystems and platform flexibility—partners or rivals that enable a richer PC game experience on handhelds can unlock high‑value niche segments.
- ASUS ROG & Microsoft (Xbox partnership) — Windows‑based high‑performance handhelds launched with AMD Ryzen AI Z2 series silicon represent a premium performance play and a clearer Xbox/PC ecosystem push. Strategic takeaway: This collaboration signals an aggressive bid to capture AAA portable gamers who demand native Windows compatibility and Game Pass integration.
- Lenovo — Experimentation with form factors, most visibly a foldable POLED concept, signals an exploratory innovation agenda aimed at expanding use cases beyond gaming (productivity, streaming). Strategic takeaway: Manufacturers focusing on form factor and multi‑use propositions can open new TAM adjacent to pure gaming.
- Sony & Microsoft (streaming and ecosystem strategies) — Sony’s handheld streaming approach and Microsoft’s device ecosystem partnerships show that cloud streaming is now a complementary, not entirely substitutive, route—especially where high‑latency reliability improves. Strategic takeaway: Content owners should view cloud as an extension of device strategy that can accelerate monetization in markets with constrained hardware access.
- Specialist OEMs (AYANEO, GPD, Anbernic, Powkiddy) — These firms address enthusiast and budget segments, though they face margin pressure from component cost volatility. Strategic takeaway: Success here depends on tight BOM control, targeted feature sets, and community engagement.
- Peripheral & cloud device players (Logitech, Razer) — Positioning ranged from cloud‑first handhelds to accessory ecosystems. Strategic takeaway: Hardware accessory companies can monetize cross‑platform compatibility and service partnerships without owning the full stack.
Industry dynamics and near‑term risks
Several cross‑cutting themes will shape 2026 outcomes:
- Component cost pressure — Demand for high‑density DRAM and advanced display panels, coupled with semiconductor export controls, has raised BOM volatility. Companies must model scenarios where component inflation persists and plan protective procurement and pricing strategies accordingly.
- Battery and regulatory compliance — Evolving regional battery safety and energy efficiency standards require proactive certification roadmaps, especially for devices integrating higher‑capacity batteries or new fast‑charge tech.
- Geopolitics — US‑China trade tensions and controls on advanced silicon exacerbate sourcing complexity, making flexible manufacturing footprints and alternative supplier development strategic imperatives.
- Form factor innovation — Foldable displays and hybrid designs present an opportunity to broaden use cases, but they also raise cost and reliability risks that require staged commercialization plans.
Practical recommendations for 2026 strategy
Based on our analysis, PW Consulting recommends the following actionable measures for executives planning for 2026:
- Prioritize supply resilience — Establish dual‑source relationships for critical components, lock in key long‑lead items through strategic pre‑orders, and create modular BOMs that allow feature‑level downgrades without reengineering.
- Align device strategy with content economics — If you control first‑party content, favor hardware decisions that maximize lifetime value (backward compatibility, cross‑buy incentives). Platform players without owned content should pursue partnerships and service bundling to capture recurring revenue.
- Differentiate via UX and ecosystem — Performance alone will not guarantee share. Invest in storefront UX, cross‑device saves, and cloud‑assisted features that lower friction for users moving between devices and living rooms.
- Embed regulatory and sustainability costs early — Factor battery certification, take‑back programs, and energy labeling into early cost models to avoid late‑stage compliance shocks.
- Leverage strategic M&A — Pursue tuck‑ins for middleware, display supply relationships, or cloud streaming partners to accelerate capability building without multi‑year in‑house development timelines.
Next steps and where to access the full intelligence
PW Consulting’s Worldwide Portable Gaming Consoles Market report delivers the forecasts, scenario models, and competitive playbooks executives and investors need to make confident 2026 decisions. The report contains the full segmentation datasets, regional analyses, channel breakdowns, and downloadable financial models that are intentionally summarized here to preserve commercial value.
For immediate access to the comprehensive dataset, subscriber‑only appendices, and bespoke advisory engagements (including a tailored 90‑day action plan and supplier risk audit), please visit PW Consulting’s research portal and request the full report package.
Prepared by PW Consulting’s Global Head of Industry Analysis, this market study combines proprietary shipment tracking, supplier interviews, and scenario modelling to deliver pragmatic recommendations—bridging boardroom strategy with factory‑floor decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Gaming Consoles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Computer Consulting Services Market to Expand from USD 865.0 Billion in 2025 to USD 1.50 Trillion by 2032 at an 8.2% CAGR — North America Leads with USD 327.7B; Top‑5 Firms Hold 24.1%
By pmarketresearch, 2026-08-12
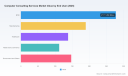
Computer Consulting Services Market 2026: Strategic Imperatives from PW Consulting
PW Consulting’s newest market research release, Computer Consulting Services Market — 2026 Edition, frames a decisive moment for CIOs, procurement chiefs, and private equity investors planning enterprise technology allocations this year. With a robust compound annual growth rate (CAGR) of 8.2% and a global services market that reached an estimated USD 865.0 Billion in our 2025 base year, our analysis projects sustained expansion through 2032 — underlining both scale and the structural shifts reshaping how organizations buy, contract and consume IT consulting services.
Digital Trunking Intercom Market
Why this report matters for 2026 decision cycles
Corporate technology roadmaps for 2026 must confront three simultaneous forces: accelerated adoption of AI and real-time data architectures; intensifying regulatory and operational resilience requirements; and continued pressure on total cost of ownership driven by labor market dynamics. PW Consulting’s study synthesizes these forces into a pragmatic playbook. The report translates macro growth (with a forecasted pathway extending to a projected market north of USD 1.5 Trillion by 2032) into tangible, time-bound actions — enabling leaders to prioritize investments that preserve optionality while capturing near-term value.
Totem Pole PFC Market
What the research reveals (high level)
- Market momentum is structural, not cyclical: the services market has expanded markedly since 2020 and our base-year analysis shows continued year-on-year growth into 2026 and beyond.
- Vendor ecosystems are expanding around data, cloud and AI platforms. Strategic M&A, platform plays and managed offerings are re-shaping competitive advantage — creating new choices but also new integration and governance imperatives for buyers.
- The provider landscape remains fragmented. Top-tier firms capture a meaningful share, yet overall concentration is moderate (our concentration analysis shows a three-firm and five-firm share that underlines available room for specialist players and new entrants).
- Regulation and labor cost trends are now first-order considerations in vendor selection, contract design, and sourcing strategy.
Practical content inside the report
This is a practitioner’s report designed to inform active procurement and strategy decisions in 2026. Core deliverables include:
AI Tool for Aviation Market
- Proprietary market-sizing and forecast model (historical 2020–2025, forecast 2026–2032) with scenario lanes for macro, technology adoption and regulatory shock events.
- A vendor assessment framework with scored dimensions for capability depth, delivery footprint, platform partnerships, IP controls, pricing models and migration velocity.
- Go-to-market playbooks and procurement templates tailored for enterprise buyers — including phased engagement models (proof-of-concept → scale → run), outcome-based contracting clauses, and performance SLAs mapped to business outcomes.
- Technology adoption timelines and capability roadmaps for AI, hybrid cloud, real-time data streaming, and cybersecurity, highlighting typical adoption lags, integration costs and break-even horizons.
- Risk registers and regulatory compliance checklists that align operational controls with the latest rules affecting IT service providers and their clients.
- Financial impact tools: TCO comparators, build-vs-buy calculators and vendor selection decision trees calibrated to industry archetypes.
To preserve strategic value, the report intentionally reserves granular regional and subsegment-level revenue tables for the full release. Readers looking to obtain deep segmentation, vendor-specific revenue splits, and downloadable model files should refer to the report subscription page.
Competitive landscape — how leading firms are positioning in 2026
The report profiles incumbent global firms and highlights how each is adapting to the era of AI, cloud-native architectures, and elevated resilience requirements. High-level takeaways:
- Accenture remains the archetypal integrator: broad industry reach, deep transformation practice, and aggressive investment in cloud, AI and industry cloud platforms. Its emphasis on outcome-oriented delivery makes it a frequent partner for large-scale modernization programs.
- IBM Consulting is doubling down on real-time data and hybrid cloud capabilities. A major strategic step in 2026 was the completion of a transformational acquisition to bolster real-time streaming and enterprise AI workflows — a capability set that materially alters turnkey options for clients building event-driven architectures.
- Deloitte continues to blend traditional consulting excellence with technology modernization services, focusing on enterprise systems modernization, cybersecurity and risk advisory — attractive for highly regulated sectors.
- Capgemini and other engineering-led firms are leveraging strong domain engineering capabilities and industry-specific IP to win complex digital engineering and cloud migration engagements.
- Tata Consultancy Services, Cognizant, Infosys and Wipro maintain scale advantages in global delivery, hybrid sourcing models and broad platform partnerships, enabling cost-competitive, rapid delivery for extensive transformation programs.
Collectively these providers define the strategic “shelf” from which most large enterprises will procure services. Yet our market-concentration analysis shows meaningful headroom for specialized firms and new entrants to capture value in niche verticals and emerging capabilities.
Recent developments shaping 2026 strategy
- Strategic M&A has accelerated platform consolidation and capability stacking across consulting leaders. Notably, a leading global consulting firm completed a high-profile acquisition in early 2026 to secure real-time data streaming and enterprise AI orchestration capabilities — a deal with significant implications for how clients source streaming architectures and agentic AI solutions.
- Smaller scale strategic acquisitions continue to re-bundle managed services, cybersecurity, and regional delivery capabilities — enabling acquirers to rapidly fill capability gaps without multiyear organic build plans.
- Regulatory milestones (described below) and ongoing labor-market pressures are driving buyers to re-evaluate risk allocation in contracts and to build stronger compliance and audit capabilities into sourcing decisions.
Regulation, labor and resilience: non-negotiable variables for 2026
Two regulatory changes and labor-market forces demand special attention in 2026 planning:
- The EU’s Digital Operational Resilience Act (DORA) has come fully into force and now applies to financial institutions and relevant ICT service providers, raising the bar for operational risk management, testing regimes and supplier oversight. Enterprises operating in, or serving, the EU must re-baseline vendor due diligence and contractual compliance clauses.
- U.S. regulatory measures governing bulk sensitive personal data transactions have expanded compliance obligations for relevant systems and providers, increasing the need for technical controls and forensic record-keeping across service deliveries.
- On the labor side, salary inflation pressures continue to bite. Average increases across technology roles are modest but meaningful; specialized skills in AI/ML and data engineering are commanding outsized premium growth compared with general IT roles. These dynamics influence near-term project costing, retention strategies and the attractiveness of managed or outcome-based contracts.
What this means for enterprise buyers — five prioritized actions for 2026
- Re-balance vendor portfolios to manage integration and regulatory risk: favor modular contracts that allow rapid substitution of components (platform, implementation partner, and managed services) without vendor lock-in.
- Price in talent premium and design for skill obsolescence: include reskilling clauses, success-based milestones and supplier retention incentives where AI and data-science expertise are central to outcomes.
- Adopt hybrid contracting models that shift more upside to outcome metrics: clients should pilot outcome-linked pricing in greenfield or low-risk domains and expand as measurement fidelity increases.
- Embed resilience and compliance KPIs into procurement checklists: require evidence of regulatory program maturity, third-party testing and incident response readiness as part of standard RFP evaluations.
- Use scenario-based forecasting to stress-test plans: leverage the report’s scenario lanes to assess implications of accelerated AI adoption, protracted supply constraints or regulatory escalations on program timing and economics.
Methodology and rigor
PW Consulting’s market model is built on a blend of bottom-up vendor analysis, top-down macro drivers, primary interviews with vendor and buyer executives, and triangulation against public filings and proprietary engagement data. Historical series cover 2020–2025, with forward-looking forecasts for 2026–2032 across three market scenarios. The report includes downloadable model worksheets for licensed clients, enabling customized sensitivity analysis aligned with a buyer’s industry, geography and technology focus.
How to use this report in your 2026 planning
Leaders planning budgets and procurement in 2026 should use this study as both a risk matrix and a prioritization instrument. The document converts large-scale market growth forecasts into recommended investment horizons, vendor engagement sequencing, and contract design patterns that reduce integration risk while preserving upside participation in AI and cloud modernization value pools.
Because the most valuable parts of the analysis are the tactical tables, vendor scorecards and downloadable financial models, PW Consulting has structured this release as a “strategic preview.” The preview demonstrates our evidence-based approach and the direction of travel without disclosing all segment-level ratios and provider revenues — encouraging investors and enterprise buyers to access the full report for operationalized intelligence.
Next steps
- Download the full report and model package from PW Consulting’s report page to obtain segment-level forecasts, vendor revenue splits, and industry-specific playbooks.
- Schedule a briefing with our senior advisors to translate findings into a one-page action plan tailored to your organization’s 2026 budget cycle.
- Engage our vendor due diligence service to validate proposed provider selections against compliance, resilience and delivery-readiness criteria.
In an environment where technology-driven advantage increasingly depends on data velocity, resilience and talent orchestration, the choices made in 2026 will compound through the decade. PW Consulting’s Computer Consulting Services Market — 2026 Edition equips leaders with the foresight and practical tools to convert market growth into defensible, measurable outcomes.
For detailed analysis of this topic, please visit the official page: Computer Consulting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide WIPS Market to Surge from USD 1,245.5 Million in 2025 to USD 3,155.06 Million by 2032 at a 14.2% CAGR
By pmarketresearch, 2026-08-12
Worldwide WIPS Market 2026: Strategic Imperatives for Enterprises — Preview of PW Consulting’s In-Depth Analysis
As organizations accelerate digital transformation, wireless networks have evolved from peripheral convenience to mission-critical infrastructure. Our new PW Consulting market brief for the Worldwide Wireless Intrusion Prevention System (WIPS) market synthesizes five years of historical performance and a forward-looking forecast through 2032 to equip C-suite and security leaders with the strategic intelligence required to act decisively in 2026. This preview highlights the market’s macro trajectory, regulatory and technology catalysts, competitive dynamics, and the practical playbook contained in the full report — while intentionally withholding granular segment tables to preserve the incentive to consult the primary research for procurement-level decisions.
Worldwide Heavy Duty Diesel Engine Oils Market
Market Trajectory at a Glance
The WIPS market has transitioned from a niche control measure to a scalable security capability tightly coupled to enterprise networking strategies. Between 2020 and 2025 the market expanded rapidly, and by our base year (2025) the global WIPS market exceeded the billion-dollar threshold. Looking forward, our model forecasts a sustained compound annual growth rate (CAGR) of approximately 14.2% during the 2026–2032 forecast window, culminating in a multi‑billion dollar opportunity by 2032. These high-level metrics frame three core strategic realities for 2026 decision-makers:
5-leg IV Stand Market
- WIPS is now a board-level risk consideration rather than a point security control.
- Technology convergence — between WLAN, cloud management, and security analytics — amplifies the value of integrated vendor platforms.
- Regulatory mandates and spectrum expansion are accelerating demand for continuous wireless monitoring and active prevention.
Why This Matters for 2026 Strategic Decisions
For security executives planning budgets, procurement cycles, or network architectures in 2026, the WIPS market’s trajectory has direct implications for three decision domains:
Worldwide Big Data Marketing Market
- Risk Prioritization and Compliance: Mandatory and advisory regulations introduced across payments, healthcare, and critical infrastructure now explicitly reference wireless monitoring and intrusion controls. Organizations facing PCI DSS, HIPAA-related guidance, NIS2 obligations, or government compliance frameworks must operationalize WIPS capabilities as part of their control baselines — not as optional add‑ons.
- Architecture and Procurement Timing: With cloud-enabled management and AI-enhanced detection maturing rapidly, the optimal procurement window hinges on defining desired outcomes (detection accuracy, latency of mitigations, integration with SOAR/SIEM) rather than simply buying the lowest-cost appliance. Our forecast suggests that delaying modernization may increase integration costs as organizations move from bolt-on approaches to platform consolidation.
- Operational Models and Skillsets: Continuous spectrum monitoring, device fingerprinting, and automated mitigation require updated operational playbooks. Security operations centers should plan for tighter collaboration with networking teams and invest in telemetry, analytics, and incident playbooks that include wireless-specific use cases.
Regulatory and Technology Tailwinds
The WIPS market is being pulled by a combination of regulatory mandates and technological enablers. Recent regulatory shifts — including the full enforcement of PCI DSS 4.0 requirements for wireless controls, updated guidance under HIPAA frameworks, and the implementation of NIS2 in Europe — elevate wireless monitoring from best practice to compliance requirement for organizations that manage sensitive data or operate as essential services. Meanwhile, spectrum policy changes (notably expanded indoor use of the 6 GHz band) and the roll‑out of Wi‑Fi 6/6E increase RF complexity and the need for sophisticated spectrum awareness.
Technologically, the market is maturing along three vectors:
- Integrated Platform Approaches: Vendors are embedding WIPS capabilities into WLAN infrastructure and network security platforms to reduce operational friction and improve mitigation velocity.
- Cloud Management and Analytics: Cloud-native orchestration and AI/ML analytics are improving anomaly detection and reducing false positives, enabling faster, more reliable automated responses from centralized consoles.
- Standards and Certification: Government-led certification efforts for secure wireless monitoring are lowering procurement friction for public sector buyers and setting higher assurance expectations across critical sectors.
Competitive Dynamics — What Leading Vendors Are Doing
The competitive landscape is characterized by platform incumbents extending wireless security into their networking portfolios and specialized vendors innovating with cloud-first architectures and patented detection methods. Market concentration is moderate: a handful of major vendors capture a meaningful share of market value, but there remains space for niche innovators and systems integrators to differentiate on deployment model, detection accuracy, and managed services.
Key vendor trends we observed:
- Network Infrastructure Leaders: Established networking vendors are strengthening WIPS through integration with their wireless access portfolios and management controllers. Expect continued emphasis on end-to-end visibility and orchestration between access layer and security controls.
- Security Platform Consolidation: Traditional security vendors are integrating wireless threat prevention into broader security platforms, aiming to deliver unified policy and incident response across wired and wireless perimeters.
- Cloud-Native and Access-Point Innovation: Cloud-managed WIPS offerings and access points with embedded detection mechanisms are gaining traction, particularly where low operational overhead and rapid scaling are priorities.
Representative vendor activity includes product enhancements focused on AI-driven anomaly detection, ongoing feature updates to embedded WIPS modules in enterprise WLAN portfolios, and government-oriented certification work that raises assurance baselines. These movements underscore the market’s dual shift toward cloud-driven analytics and regulatory-grade assurance.
What the Full Report Provides (Practical, Actionable Content)
PW Consulting’s full research deliverable is designed as a decision-support tool for CISOs, procurement teams, network architects, and vendor strategists. The report contains:
- Comprehensive market sizing and a seven-year forecast with scenario sensitivity analysis to help you stress-test procurement and budget assumptions.
- Vendor profiles and comparative capability matrices mapping detection techniques, mitigation options, integration touchpoints, and enterprise-grade management features.
- Regulatory impact analysis translating compliance requirements into implementation checklists and control baselines for key sectors.
- Deployment playbooks that cover on-premise, hybrid, and cloud-centric operational models — including staffing, telemetry requirements, and incident playbooks tailored to wireless threats.
- Procurement frameworks and RFP templates to accelerate vendor selection while ensuring alignment to desired security outcomes rather than feature checklists.
- Risk-quantified ROI models that help you compare lifecycle costs of retrofit WIPS versus integrated platform approaches under multiple threat and compliance scenarios.
Note: this preview intentionally refrains from reproducing granular segment and regional breakdowns. The full report contains detailed tables and appendices that are essential for vendor short-listing and budget approvals.
Strategic Recommendations for 2026
Based on our analysis, PW Consulting recommends the following pragmatic steps for organizations formulating WIPS strategies in 2026:
- Map WIPS to Business-Critical Assets: Prioritize deployment where cardholder, healthcare, or operational technology traffic terminates. Use a risk lens to sequence rollout and then expand coverage iteratively.
- Favor Integrated Detection and Response: Assess vendors on their ability to integrate wireless telemetry into broader security operations and automation platforms to reduce mean time to detect and respond.
- Plan for Spectrum Complexity: Include spectrum monitoring capabilities and RF analytics in procurement requirements to ensure visibility across legacy and new frequency bands.
- Adopt a Compliance-First Baseline: Align WIPS implementations with applicable regulatory frameworks to avoid remediation costs and penalties; document controls to streamline audits.
- Consider Managed and Co-Managed Models: Where in-house skill gaps exist, evaluate managed WIPS or co-managed options to accelerate time-to-protection while transferring operational overhead.
For Vendors and Investors
Vendors should prioritize interoperability, explainable AI for detection confidence, and simplifying deployment footprints. Investors can look for scale-ups that combine high-fidelity detection with low operational false-positive rates, or service providers that offer turnkey managed WIPS with compliance guarantees. Market concentration indicates meaningful opportunity for both established incumbents to expand share and for specialized innovators to capture vertical pockets where unique capabilities (e.g., government certifications or patented detection methods) create defensible differentiation.
Conclusion — How to Use This Preview
WIPS is now a central component of enterprise security posture and compliance strategy. Our forecast and market analysis demonstrate sustained, above-market growth driven by regulatory mandates, wireless technology shifts, and vendor innovation. This preview provides the strategic context and high-level implications that should inform 2026 planning cycles; the full PW Consulting report delivers the actionable segmentation data, vendor comparisons, and procurement tools you will need to operationalize these insights.
To access the detailed segment tables, vendor matrices, and deployment playbooks that underpin the recommendations in this preview, please consult the full Worldwide WIPS Market report — it is designed to be the operational manual for your 2026 wireless security roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Wireless Intrusion Prevention System (WIPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 18.24% CAGR for Worldwide Battery Manufacturing Software Market — Rapid Expansion Expected Through 2032
By pmarketresearch, 2026-08-12
Worldwide Battery Manufacturing Software Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I am pleased to introduce our latest market research brief: the Worldwide Battery Manufacturing Software Market. Built on a rigorous historical baseline (2020–2025) with a declared base year of 2025 and a forward-looking forecast window of 2026–2032, this study translates fast-moving technological, regulatory and operational dynamics into actionable guidance for executives planning capital and product strategies in 2026.
Worldwide Cloud Computing Chips Market
Market Trajectory: A Macro View You Can Act On
Battery manufacturing software is in a sustained expansion phase. In monetary terms (USD, revenue unit: Million), the market expanded from roughly 510.45 in 2020 to 1,127.29 in our base year of 2025. Our forecast projects continuation of this momentum into the coming decade — with the market crossing the mid-thousands by 2032. The compound annual growth rate for the forecast window stands at 18.24%, reflecting accelerated adoption across gigafactories, cell pilot lines, EV supply chains and utility-scale storage projects.
Worldwide Organic Tableware Market
This macro-scale growth is not abstract: it directly influences supplier selection, capital planning, digital transformation sequencing and workforce strategy. The numbers embedded in this report equip leaders to size near-term budgets, stress-test multi-year roadmaps and build procurement clauses that align software delivery with production ramp milestones.
Basic Travel Insurance Market
Why 2026 Is an Inflection Year
- Regulatory urgency: New compliance regimes — notably the EU battery passport and associated requirements for carbon-footprint declarations and component traceability — become increasingly binding within the next two years. For large manufacturers, this drives mandatory investments in traceability and data sovereignty capabilities.
- Policy-driven onshoring: Public incentives and industrial policy have already catalyzed a dramatic increase in domestic battery output in key markets. This rapid onshoring amplifies the need for interoperable software stacks that can be integrated across newly built gigafactories.
- Operational leverage: Empirical industry studies show targeted digitalization use cases — from predictive quality to traceability automation — can materially lower staffing needs and reduce energy and material waste. Energy-tracking and optimization alone can deliver sizeable reductions in consumption at discrete process stages, while predictive approaches significantly reduce startup scrap and ramp-time losses.
- Cyber and data risks: Connected manufacturing environments for batteries require explicit compliance with cybersecurity frameworks and cryptographic standards; secure communications and update mechanisms are no longer optional.
What the Report Delivers — Practical, Executable Intelligence
This research is designed as a decision-support tool for CXOs, product leaders, plant managers and procurement teams. Our deliverables emphasize operational utility over academic completeness; in other words, we show you how to act.
- Market sizing and scenario forecasts: Detailed top-line sizing for historical and forecast periods (2020–2032), with stress-tested scenarios that reflect variation in capex cycles, policy shifts and EV demand trajectories.
- Buyer-focused playbooks: Use-case driven procurement templates and RFx language that translate desired KPIs (yield, energy intensity, traceability latency, cybersecurity posture) into contract milestones and acceptance tests.
- Implementation roadmaps: Stepwise deployment blueprints for MES/MOM, digital-twin and analytics rollouts across pilot, scale-up and gigafactory stages — including suggested pilot metrics and governance models.
- ROI and TCO modeling: Financial templates to evaluate build-vs-buy, capex/OPEX tradeoffs, and payback timing under different yield and energy-saving scenarios.
- Vendor scorecards and gap analyses: Qualitative and quantitative assessments of incumbent and specialist software vendors across capability dimensions — from traceability and quality management to AI-driven analytics and edge/cloud architectures.
- Regulatory and cybersecurity checklists: Practical checklists and control mappings against contemporary standards and requirements — for example, guidance that aligns traceability workflows with forthcoming battery passport rules and cybersecurity controls based on recommended standards for connected manufacturing.
- Data architecture patterns: Reference designs for secure, scalable data flows (edge ingestion, canonical data models, lineage, and cloud-analytic pipelines) that prioritize interoperability and vendor portability.
- Case studies and playbooks: De-identified case studies that show how leading adopters compressed ramp times, reduced scrap and improved first-pass yield through specific software configurations and organizational changes.
To preserve competitive sensitivity of our clients and to respect commercial confidentiality within vendor contracts, the report intentionally avoids publishing vendor-specific pricing schedules or granular account-level contract terms. Detailed segmentation tables and proprietary model outputs are available in the full report for registered users.
Competitive Landscape — Who Is Shaping Solutions Today
The vendor ecosystem combines large industrial-software incumbents, controls-and-automation leaders, and nimble analytics specialists. Each group brings different strengths: scale and integration breadth on one hand, focused analytics and fast iteration on the other.
- Industrial incumbents and automation leaders: Companies such as GE Vernova, Siemens, Rockwell Automation, ABB and Panasonic Connect provide broad MES/MOM portfolios and deep integration with plant automation stacks. Their value proposition centers on end-to-end production visibility, quality governance, and standardized process planning, all critical for gigafactory-scale operations.
- Enterprise analytics and battery-specialist vendors: Firms like Voltaiq, PDF Solutions and Energsoft offer targeted analytics platforms that span R&D through manufacturing, enabling data-driven failure-mode identification and predictive quality control that complement MES capabilities.
- Modular and AI-focused players: camLine (Elisa IndustrIQ) and others supply MES/MOM variants with strong traceability and AI-driven process controls — attractive for manufacturers who want faster time-to-value and modular implementations.
Recent product launches underscore strategic positioning across the ecosystem: Honeywell’s Battery Manufacturing Excellence Platform (Battery MXP) — an AI-enabled solution introduced in mid-2024 — targets yield improvement and ramp compression. Panasonic Connect’s Syncora platform, announced in late 2024, is positioned to accelerate MES-driven digital transformation in nascent domestic production hubs. These developments point to intensified competition around AI-driven optimization and full-stack MES offerings.
Strategic Priorities and Technology Imperatives for 2026
- Traceability and data sovereignty: Build architectures that can satisfy compliance regimes (battery passports and similar disclosures) while protecting IP and sensitive process data.
- Modular MES integration: Prioritize vendors who support phased rollouts and open APIs to avoid lock-in and enable best-of-breed analytics overlays.
- AI for yield and energy: Deploy analytics that address both quality (reducing scrap and improving cell yields) and energy optimization — use cases with clear, measurable ROI.
- Cybersecurity by design: Adopt secure communication standards and update mechanisms (strong encryption, mutually authenticated TLS channels, and secure firmware/update flows) aligned to industry recommendations.
- Workforce and process change management: Combine automation with reskilling programs; quantify labor cost exposure and design automation projects that deliver measured headcount and efficiency gains.
- Pilots with KPI discipline: Execute short-cycle pilots with clearly defined acceptance criteria (yield delta, ramp-time reduction, MTTR improvements) to de-risk scale deployments.
How Executives Should Use This Report in 2026
- Use the market forecast and scenario outputs to justify multi-year software budgets and align them to production-capacity milestones.
- Run vendor shortlists through the supplied scorecards and RFx templates to capture contractual protections tied to production KPIs.
- Adopt the report’s ROI models to compare automation investments across cell lines and facility expansions, integrating energy and labor-savings assumptions.
- Leverage the regulatory and cybersecurity checklists to accelerate compliance readiness and reduce audit exposure ahead of mandated regimes.
- Prioritize pilots that combine MES/MOM, process analytics and digital-twin capabilities to deliver measurable ramp and yield outcomes within 6–12 months.
Conclusion — A Teaser for Deeper, Transactional Intelligence
The Worldwide Battery Manufacturing Software Market is transitioning from niche digital projects to central pillars of factory economics and regulatory compliance. With the market expanding rapidly — following an 18.24% CAGR over the forecast period and a multi-fold increase in absolute market size between 2020 and 2032 — the decisions you make in 2026 will determine whether your software choices accelerate or constrain production, compliance and margin outcomes.
PW Consulting’s full report contains the granular segmentation, vendor benchmarking matrices, contract language templates and detailed scenario model outputs that support procurement, investment and M&A decisions. To access the complete data tables and our executable toolkits (including per-solution implementation playbooks and sample RFx documents), please visit the report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide Battery Manufacturing Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Tilt & Turn Window Handles Market Set to Expand at a 5.23% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Handles of Tilt & Turn Windows Market — Strategic Briefing for 2026 Decision-Makers
Executive preview
As PW Consulting’s lead industry analyst, I present a targeted strategic briefing drawn from our comprehensive Worldwide Handles of Tilt & Turn Windows Market report (base year 2025). The product category—specialised handles and related hardware for tilt & turn windows—sits at the intersection of building energy-performance regulation, materials cost volatility, and accelerating smart-home integration. Our analysis finds the market has recovered from mid‑cycle volatility and is tracking a steady expansion trajectory, underpinned by regulatory retrofit demand and rising preference for durable metal-based hardware. The market size in 2025 was measured at USD 648.5 million and, given current dynamics, we project steady growth at a compound annual growth rate (CAGR) of 5.23% across our 2026–2032 forecast horizon, with long‑term upside if smart‑home and energy retrofits accelerate.
Worldwide Infiltration Marketing Market
Why this briefing matters for 2026 strategic planning
- Pinpointing inflection points: The next 18–36 months will determine winners in both specification‑driven commercial projects and high-volume residential retrofit channels. Companies that move early on energy‑compliant and connected hardware will capture disproportionate share.
- Cost‑to‑value pressure: Manufacturers face higher input costs (notably aluminum) while buyers demand enhanced functionality. Strategic choices on material mix, finish technologies, and supply contracts will materially affect margin outcomes in 2026.
- Consolidation and partnership windows: Industry concentration is moderate—top manufacturers command meaningful but not dominant shares—creating attractive M&A and joint‑venture opportunities for platform expansion or geographic scale.
Market outlook — a data‑led snapshot (high level)
From a macro perspective the handles market shows resilience and structural expansion. After a modest mid‑cycle dip, total market revenue reached USD 648.5 million in 2025. Under our base scenario—reflecting current regulation, construction and retrofit pipelines, and normalised raw‑material inputs—the market grows at a 5.23% CAGR during 2026–2032, reaching an elevated market size by the end of the forecast period. This trajectory reflects steady demand for high‑performing hardware in both new construction and retrofit markets, with periodic acceleration tied to major regulatory milestone years and smart‑home adoption cycles.
Worldwide Productivity Bots Software Market
Dynamics shaping supplier and buyer strategy
- Regulation as demand lever: Updated energy performance standards in major jurisdictions (notably the EU’s EPBD revisions and the UK’s Future Homes/Part L updates) are driving window replacement and specification upgrades. Tilt & turn systems—due to their airtightness, ease of retrofit, and compatibility with advanced locking hardware—are frequently specified in compliance projects.
- Raw‑material volatility: Producer prices for aluminium mill shapes rose materially in 2025 (notable year‑over‑year increases). This has immediate cost implications for metal‑dominant handle portfolios and places a premium on procurement sophistication—longer contracts, metal hedging or strategic alloy substitution where performance allows.
- Material and finish priorities: Aluminum‑based handles continue to gain share where corrosion resistance and weight are priorities; zinc and stainless offerings retain roles where cost or design premium drive selection. Metal finishes and coatings that extend lifespan in coastal or corrosive environments are becoming specification differentiators.
- Smart integration and standards: Smart window hardware is transitioning from niche to mainstream. Recent product launches supporting Matter and robust radio ecosystems create a new vector of value—security, occupant comfort and system‑level energy optimisation. Suppliers who integrate open, cross‑platform connectivity will find easier entry into premium retrofit projects and OEM spec lists.
- Form and fabrication: Trends toward concealed hinges, multi‑point locking and special‑shape window solutions (round tops, trapezoids) are influencing handle design and mounting systems—requiring closer collaboration between handle makers and hardware system suppliers.
Competitive landscape — positioning and implications
The competitive field blends established European system houses with value‑oriented regional suppliers and design‑led premium brands. Market concentration is moderate—top three players collectively hold a meaningful but not overwhelming portion of market sales, leaving room for nimble specialists and regional consolidators.
Worldwide Inorganic Waveplates Market
- HOPPE (Germany) — https://www.hoppe.com
Strengths: Broad design portfolio across multiple series and finishes; strong brand recognition in Europe; integrated security features for tilt & turn. Strategic implication: HOPPE’s design depth makes it a preferred partner for high‑quality residential and bespoke commercial specifications.
- Gretsch‑Unitas (G‑U) (Germany) — https://www.g-u.com
Strengths: Certified hardware meeting EN standards; lockable handle options; engineering focus for modern systems. Strategic implication: G‑U is well positioned for spec‑led projects requiring tested, certified performance—an important differentiator in regulatory procurement.
- MACO (Austria) — https://www.maco.eu
Strengths: Integrated turn & tilt systems for different profile materials; strong OEM and fabricator relationships. Strategic implication: MACO’s multi‑profile capability supports scale through fabrication channels—key for volume growth in retrofit markets.
- Roto Frank (Germany) — https://www.roto-frank.com
Strengths: Focus on aluminium solutions, concealed hinges, and long‑life corrosion performance; recent product updates emphasize design and endurance. Strategic implication: Roto is the go‑to for premium aluminium systems and international manufacturers seeking robust aesthetic and functional solutions.
- Siegenia (Germany) — https://www.siegenia.com
Strengths: Smart handle development and Matter‑ready 2nd generation products; recent FENSTERBAU showcase. Strategic implication: Siegenia’s connectivity roadmap is a blueprint for entrants pursuing smart‑home and retrofit value pools—expect accelerated adoption where installers can upsell connectivity.
- Winkhaus (Germany) — https://www.winkhaus.com
Strengths: High‑performance hardware solutions including concealed hinge options; strong engineering pedigree. Strategic implication: Winkhaus competes strongly on performance features for premium windows and special shapes.
- ASSA ABLOY Fenestration — https://www.assaabloyfenestration.com
Strengths: Global scale, corrosion‑resistant aluminium solutions, and offerings for special shapes. Strategic implication: Benefitting from group scale, ASSA ABLOY targets international OEM channels and specification projects that demand global supply consistency.
- Trojan (UK) — https://www.trojan.co.uk
Strengths: Value and performance for uPVC and common profiles. Strategic implication: Trojan is a go‑to in price‑sensitive segments where installers prioritise reliability and cost control.
- FPL Hardware (US) — https://fplhardware.com
Strengths: Range tailored for tilt‑turn and casement applications; US‑market orientation. Strategic implication: Regionalisation matters—FPL’s portfolio illustrates the advantage of tailoring SKUs to local profile systems and distributor expectations.
- Formani (Netherlands) — https://www.formani.com
Strengths: Design‑led, award‑winning premium handles for architectural projects. Strategic implication: Formani captures premium margins where aesthetics and brand cachet matter, especially in high‑end European retrofits and new build projects.
Recent signals worth watching in 2026
- Siegenia’s launch of a Matter‑version smart handle (Jan 2026) signals a migration to industry standard smart protocols—buyers will increasingly request Matter compatibility in tender documents.
- Roto’s continued promotion of aluminium‑focused tilt & turn systems (2025 updates) highlights ongoing demand for corrosion‑resistant, premium aluminium solutions in international markets.
- Trade show activity (e.g., new products showcased at IBS 2026) indicates suppliers are pushing integrated system narratives—handle + hardware + connectivity—rather than standalone SKUs.
Actionable strategic playbook for 2026
- Procurement and cost management: Lock targeted aluminium volumes under multi‑year contracts where feasible; assess alloy substitution or partial material mix shifts for non‑structural components to protect margin against metal price spikes.
- Product strategy: Prioritise development of energy‑compliant handle assemblies and Matter‑capable smart handles. Invest in robust radio links and cyber‑security certification to reduce installation friction and reassure specifiers.
- Channel and go‑to‑market: Accelerate partnerships with fabricators and window system OEMs. Offer bundled hardware + connectivity packages to installers to increase attachment rates in retrofits.
- Aftermarket and services: Develop retrofit kits and certification packages for energy‑upgrade projects (labelling, testing, and installer training) to capture high‑margin downstream revenues.
- M&A and partnerships: With moderate top‑end concentration, there is strategic logic to bolt‑on acquisitions that fill material, connectivity, or geographic gaps—targeted tuck‑ins can rapidly expand specification reach.
- Regulatory and standards engagement: Proactively engage with certification bodies and standards consortia to ensure product compliance and to influence emerging test protocols for smart window hardware.
What our full report delivers (operational value)
The PW Consulting report goes beyond headline growth to provide decision-ready deliverables for 2026 planning cycles, including:
- Proprietary market sizing and scenario forecasts through 2032 with sensitivity to raw‑material price paths and regulatory accelerants.
- Supply‑chain mapping and a cost‑to‑serve model that isolates procurement levers and margin pressure points.
- Detailed competitor profiles, product matrices, and go‑to‑market playbooks for market entry, expansion, and consolidation strategies.
- Regulatory impact assessment across major jurisdictions and a compliance roadmap for manufacturers and specifiers.
- Commercial tools: pricing frameworks, bundling strategies, and aftermarket monetisation options tailored to manufacturers, distributors and installers.
To respect the role of this briefing as a prelude, we intentionally reserve the granular segment and regional splits, SKU‑level unit economics and modelled price‑elasticity matrices for the full report and interactive dashboard available on our site.
How to use this insight immediately
- Run a 90‑day procurement stress test: model current supplier contracts against a +20% aluminium price scenario and quantify margin exposure.
- Pilot Matter‑capable handle deployments with two installer partners in retrofit projects to validate installation workflows and capture first‑mover premium data.
- Identify one regional M&A target that closes a capability gap (connectivity, coating tech, or fabrication scale) and initiate commercial diligence.
Next steps
PW Consulting’s full Worldwide Handles of Tilt & Turn Windows Market report is the practical resource for teams preparing 2026 budgets, R&D roadmaps, or M&A pipelines. For bespoke briefings, scenario runs, or to access the full dataset and interactive dashboard (including regional and subsegment detail), contact our research team and download the report from the PW Consulting portal. Use the intelligence to convert regulatory and material volatility into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Handles of Tilt & Turn Windows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insights: Worldwide Electrical Orchard Sprayer Market to Reach USD 1,000.44 Million by 2032
By pmarketresearch, 2026-08-12
Worldwide Electrical Orchard Sprayer Market — Strategic Outlook for 2026 Decision-Making
PW Consulting is pleased to announce the release of our in-depth market research brief on the Worldwide Electrical Orchard Sprayer Market. Built to be immediately usable by executive teams, product leaders, procurement officers and investors, this briefing synthesizes five years of historical performance, a detailed forward-looking model, and practical decision frameworks to guide capital allocation and go-to-market choices in 2026. The analysis demonstrates where value will be created in the next wave of orchard electrification while intentionally reserving core segmentation tables in order to drive clients to the full report for the granular inputs that underpin commercial decisions.
VCSEL Laser Chips Market
Executive snapshot
Electrification of orchard spraying is no longer a pilot-stage curiosity. Our market model values the global market at approximately USD 631.24 Million in the base year 2025 and forecasts growth to about USD 1,000.44 Million by 2032, representing a compound annual growth rate (CAGR) of 6.8% across the 2026–2032 forecast window. The market has accelerated from the historical period of 2020–2025, driven by advances in battery energy density, autonomy and precision application technologies, and by a faster-than-expected willingness by growers to trade capital expense for operating cost reduction and regulatory compliance.
Worldwide Infrared Transmitting Glass Market
Why this matters for 2026 decision-makers
- Capital allocation: Manufacturers and component suppliers must decide whether to prioritize electrified orchard platforms, hybrid architectures, or modular retrofits. The mid-single-digit CAGR through 2032 signals a growth runway long enough to justify factory retooling, but decision timing will affect margin and market share.
- Technology integration: Battery systems and autonomy stacks are now sufficiently mature to deliver full-shift operation in many orchard use-cases. Third‑party battery packs (notably 60–70 kWh-class systems) have been demonstrated to support 10–12 hours of continuous operation in representative deployments, removing a key operational barrier for adoption.
- Operational economics and sustainability: Precision spot-spraying using AI-powered weed detection has been shown in field demonstrations to cut chemical usage substantially. Where installed, these systems materially reduce input spend and regulatory compliance risk, changing the payback calculus for end users.
- Channel and service model implications: With electrified and autonomous platforms, the aftermarket and software subscription layers become as important as hardware sales. Dealer networks that move from pure equipment sales to outcome-based services will capture disproportionate lifetime value.
What our report delivers — practical tools and proven frameworks
PW Consulting’s report is structured as a commercial playbook for 2026 implementation. We pair a transparent market model with actionable tools designed to accelerate good decisions and de-risk execution:
CTA Head and Neck Analysis System Market
- Proprietary market model (Excel): fully auditable top‑down and bottom‑up demand estimates, scenario toggles (adoption curves, battery-cost declines, regulatory tightening) and sensitivity analysis to test strategic options.
- Five strategic scenarios for 2026–2032: baseline, accelerated electrification, delayed battery rollout, rapid autonomy adoption, and fragmented standards — each with P&L impact for OEMs and expected payback periods for growers.
- Vendor scorecards and supplier due-diligence templates: a standardized assessment across technology readiness, manufacturing scale, channel strength, service capability and regulatory posture.
- Field validation case studies: operational KPIs from commercial pilots that explain the gap between lab claims and on-farm economics — including real-world duty cycles, maintenance profiles and operator acceptance metrics.
- TCO / TCA calculators and financing frameworks: factory-to-farm total cost of ownership worksheets incorporating battery life, chemical-use reductions, labour displacement, and service revenue streams to support procurement decisions and leasing structures.
- Regulatory and safety matrix: regional compliance checklists, data privacy considerations for telematics, and operator-safety design priorities for autonomous spraying in mixed-use orchard environments.
Competitive landscape — what recent moves mean
The vendor environment is transitioning from fragmented hardware specialists toward integrated systems players that combine electrification, autonomy and software. Notable industry developments tracked in the report illustrate these dynamics and the strategic responses required of incumbents and newcomers alike:
- John Deere’s integration of an autonomous electric orchard sprayer platform has been a watershed event. The acquisition completed in 2025 brings a fully electric autonomous herbicide sprayer — built around high-capacity battery packs and advanced AI weed-detection — into a global dealer network. This move signals OEM commitment to bundling autonomy, battery and telematics as a single commercial offering targeted at high-value orchard segments.
- Specialist manufacturers are doubling down on complementary strategies. Select European and Oceania-based suppliers have prioritized compact, fully electric sprayers designed for compatibility with electric tractors and small-farm ergonomics. These firms emphasize modularity, field serviceability and crop-specific application techniques (for example, recapture/recycling technologies for disease control in high-density plantings).
- Product updates from established agricultural equipment brands show a parallel playbook: incremental performance improvements in tank design and control systems paired with simplified operation for specialty crop contexts, making electric options more accessible to traditional buyers.
The net effect: a moderately concentrated market where a small group of well-capitalized OEMs and specialist innovators shape platform standards, while a broad base of niche suppliers address diverse orchard types and regional channel structures. For strategy teams, this means monitoring both headline consolidation moves and the ecosystem of accessory suppliers (battery manufacturers, AI detection software providers, retrofit specialists) that will determine who can deliver end-to-end solutions at scale.
Key operational implications and strategic imperatives for 2026
- Design for serviceability and modular upgrades: Battery and autonomy components evolve quickly. OEMs should design platforms that allow battery swaps, electronic control upgrades and sensor refreshes without full-system replacements.
- Build dealer capacity for electric and software services: Training, tooling and new parts inventories are prerequisites for scaling commercial deployments; dealers that invest here will capture aftersales revenue and reduce downtime for growers.
- Pursue strategic battery and software partnerships: Vertical integration can fast-track capability, but partnering with battery specialists and AI providers preserves capex and accelerates time-to-market.
- Create clear financing and subscription offers: Leasing batteries, offering software-as-a-service for precision application, and bundling maintenance into subscription packages materially reduce buyer friction.
- Operationalize safety and compliance: Autonomous sprayers must embed robust person-detection and automatic pause mechanisms to align with liability expectations in orchard work environments.
How growers and procurement leaders should think about 2026 purchases
- Run TCO scenarios that include chemical-use savings from precision spot-spraying and expected battery replacement cycles; the combination often materially shortens payback for high-input, labor-constrained operations.
- Require field trial data from vendors in similar crop architectures and climates. Benchmarks for spray accuracy, drift reduction and maintenance intervals should be contractually specified.
- Prioritize interoperability: if you are electrifying a fleet, choose solutions that integrate with your preferred tractor OEMs and telematics systems to avoid lock-in and stranded assets.
- Factor in dealer footprint and service SLAs: uptime in spray seasons is a business-critical KPI; ensure vendor contractual commitments reflect real-season response times.
Investor and M&A perspective
John Deere’s strategic move to internalize an autonomous electric sprayer underscores the market’s growing strategic value. Investors evaluating targets should focus on four valuation levers: IP in autonomy and detection models, proven battery integration for full-shift operations, established channel or distribution agreements, and recurring revenue potential from software and service offerings. Our report includes precedent transaction analysis and a valuation sensitivity tool built around those levers to support diligence and offer strategy.
Next steps — how to use PW Consulting’s full report
This briefing is designed to be a decision-ready trailer: it communicates the direction and the levers that matter without disclosing every cell in the model. The full PW Consulting report contains the complete, auditable market model (with regional, type and application splits), supplier scorecards with graded assessments, downloadable TCO calculators and step-by-step implementation roadmaps tailored to grower size segments and regional regulatory regimes.
For teams preparing 2026 budgets and product roadmaps, the full dataset and playbooks will materially shorten evaluation cycles and reduce execution risk. Access to vendor-level segmentation and the full scenario matrices enables precise capital planning, procurement evaluation and go-to-market sequencing that can convert the projected growth runway into defensible revenue streams.
To request the full report, the interactive Excel model, or a tailored briefing for your executive team, please contact PW Consulting through our website and reference the Worldwide Electrical Orchard Sprayer Market 2026 Briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Electrical Orchard Sprayer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Non‑Filtering Cloth Vacuum Filters Market Forecast to Hit USD 378.74 Million by 2032, Growing at a 5.85% CAGR
By pmarketresearch, 2026-08-12
Worldwide Non-Filtering Cloth Vacuum Filters Market — Strategic Outlook for 2026: A PW Consulting Preview
PW Consulting’s latest market study on the Worldwide Non-Filtering Cloth Vacuum Filters market provides an operationally focused intelligence package for executives who must make consequential 2026 decisions across procurement, product strategy, operations and M&A. This is a preview designed to demonstrate the report’s depth and immediate relevance while reserving detailed segment-level figures for the full report.
Worldwide Dioctyl Fumarate Market
Market snapshot: Growth trajectory and concentration
The non-filtering cloth vacuum filters market has shown steady expansion through the current decade. Our compiled historical database records market size growth from approximately USD 192 million in 2020 to about USD 254 million in 2025. Looking forward, the market is projected to continue expanding through the 2026–2032 forecast window, reaching roughly USD 379 million by 2032 under a compounding annual growth rate of about 5.85%.
4K Endoscopy Camera System Market
Concentration dynamics matter for strategy: the market remains moderately fragmented, with the top-three vendors accounting for under half of revenues and the top-five approaching just over half. Such a structure creates room for both niche specialists and consolidation plays, depending on technology, service depth and supply chain integration.
Worldwide Inhaler Devices Market
Why this matters for 2026 decision-making
-
Capital allocation and product development: sustained mid-single-digit CAGR signals predictable demand across core industrial end users—enough to justify targeted capex for product line upgrades and automation of manufacturing lines for synthetic yarns and woven cloths.
-
Supplier selection and risk mitigation: fragmentation combined with concentrated material inputs (polypropylene, polyester and specialized multifilament yarns) increases vendor dependency risks. Procurement strategies in 2026 must balance cost, lead-time and technical collaboration ability—particularly for high-stability, wide-format belts and high-temperature synthetics.
-
M&A and partnership discipline: the market structure supports bolt-on acquisitions for firms seeking immediate access to filtration fabrics expertise, regional footprints or specific polymer technologies. A focused due diligence framework will separate scale-driven targets from technology-led niche players.
-
Regulatory and quality-driven segmentation: increasing regulatory scrutiny in food, pharmaceutical and certain clean-water applications favors suppliers that can demonstrate food-grade certifications, hygienic manufacturing and traceable supply chains—criteria that should be embedded in 2026 supplier scorecards.
Market dynamics shaping 2026 priorities
-
Raw material tightness and cost pass-through. Polypropylene and polyester remain the dominant feedstocks for woven and non-woven vacuum filter cloths. Price volatility in these polymers, together with periodic logistic constraints, will influence manufacturers’ margin structures and contract terms in 2026. Buyers will look for vendors with upstream relationships or hedging strategies to stabilize supply and pricing.
-
Performance-driven adoption. Across mining, mineral processing and wastewater treatment, demand is being driven by requirements for improved cake dryness, faster throughput and reduced downtime. Customers are increasingly procuring tailored cloth architectures (monofilament vs multifilament, specialized coatings, edge reinforcements) and demanding validated life-cycle metrics rather than simple unit price comparisons.
-
Certification and hygiene. Where vacuum filter cloths interface with food processing or pharmaceutical streams, compliance with food-grade standards (FDA, CE-equivalent hygiene standards) is a gating factor—affecting which vendors can participate in shortlists and how product life-cycle documentation is managed.
-
Technology and manufacturing scale. The ability to produce wide-format belts with dimensional stability and abrasion resistance (some vendors report belt widths of several meters) differentiates suppliers in industries requiring large-area filtration. Proprietary closures, edge reinforcement techniques and polymer blends are practical competitive levers.
Competitive landscape — profiles and positioning
The market combines global engineering groups, vertically integrated manufacturers and specialized European fabric innovators. The following is an analytical primer on five emblematic competitors identified in our study and the strategic implications for buyers and investors.
-
Micronics Engineered Filtration Group (part of Cleanova) — A US-based custom-engineering leader with deep capabilities across rotary disc, drum and horizontal belt filters. Micronics’ strength lies in application engineering and systems-level integration, making them a preferred partner for operations-constrained industrial users seeking turnkey upgrades and performance validation across mining, alumina refining and wastewater. For 2026 procurement strategies, Micronics is a candidate where technical co-development and long-term service agreements are priority selection criteria.
-
Bolian Filtration Solutions (Liaoning Bolian) — A China-headquartered manufacturer focused on woven filter cloths for a wide range of vacuum filtration variants and expanding into energy-related niches such as lithium battery processing. Recent activity shows an emphasis on industry engagement—exhibitions and supplier awards—indicating an aggressive commercial push and growing recognition among large OEMs and process operators. For buyers, Bolian represents a cost-competitive, rapidly scaling alternative with improving credentials for global project supply.
-
GKD Group (GKD Gebr. Kufferath AG) — A German supplier offering belt systems and cloths with integrated know-how in vacuum box design and wash-water management. GKD’s proposition is systems-oriented: cloth + hardware + spares. Companies prioritizing uptime and system harmonization often favor this model, as it reduces specification risk and simplifies warranty and maintenance pathways.
-
Testori S.p.A. — An Italian supplier focused on polymer-variant filter media and cake-discharge engineering. Testori’s strength is customization in polymer selection and yarn architecture, making them viable for applications where precise cake-release behavior and polymer compatibility are critical—food and specialty chemicals among them.
-
K2TEC — A French firm noted for material breadth (PP, PES, PA, PVDF, PTFE) and mechanical innovations such as patented closures and reinforced edges. K2TEC’s technical IP is valuable for operations requiring very fine control over pore size and mechanical durability—pharmaceuticals, fine chemicals and abrasive mineral processing.
Recent vendor movements and what they signal
-
Trade-show activity and supplier awards are more than marketing; they are barometers of market momentum and procurement recognition. Bolian’s sustained presence at major filtration exhibitions and recent supplier commendations in 2026 signal rising commercial acceptance and should prompt global buyers to include them in competitive bid lists where cost and scale matter.
-
European and US suppliers continue to compete on engineering depth and service models, while Asian manufacturers increasingly offer competitive lead-times and modular customization. Expect supplier strategies in 2026 to converge around hybrid offers: engineering + localized manufacturing footprints.
What the full PW Consulting report delivers (practical, executable content)
The full report is structured for action. Key deliverables include:
-
Transparent market sizing and conservative-to-optimistic scenario modelling for 2026–2032, including sensitivity testing on polymer price swings and capex cycles in mining and wastewater sectors.
-
A competitive scorecard with supplier capability maps, including manufacturing footprint, material range, certifications, lead-time profiles and aftermarket service models—designed to fast-track vendor shortlisting.
-
Procurement playbook for 2026: recommended contractual clauses, SLAs tied to cake dryness and belt lifetime, inventory buffers and raw-material pass-through templates.
-
Operational improvement guide: process KPIs to validate cloth upgrade ROI (cake moisture reduction, cycle-time uplift, cloth service life) and a template workshop agenda for supplier co-engineering pilots.
-
M&A and partnership framework: valuation multipliers for niche fabricors, integration risk checklist, and price/volume threshold models to justify bolt-on acquisitions.
-
Regulatory and compliance appendix: food-grade and hygiene checklists mapped to procurement gate criteria for 2026 tenders.
How to use the preview in 2026 planning
-
Prioritize proof-of-value projects: use short pilot programs to validate supplier claims on cloth life and cake moisture benefits before committing to large rollouts.
-
Lock flexible supply agreements: structure contracts with optionality on volumes to protect against raw-material cost swings while preserving preferred pricing for scale.
-
Embed certification milestones: require evidence of hygiene and material certifications for food and pharma applications early in the RFP phase to avoid late disqualifications.
-
Consider targeted acquisitions: small fabricators with IP in edge-reinforcement or closure systems may be high-impact, lower-cost ways to accelerate technical capability.
Next steps — where to get the complete intelligence
This preview highlights the broad contours and strategic imperatives the PW Consulting report provides to executives planning for 2026. The full report contains the granular supplier matrices, validated methodology, scenario models and downloadable procurement templates instrumental for executable decisions. For procurement directors, operations heads and strategy teams preparing budgets and R&D roadmaps in 2026, the complete report is the practical tool to convert market opportunity into measurable outcomes.
Access the full Worldwide Non-Filtering Cloth Vacuum Filters Market report on our website to download the comprehensive dataset, supplier scorecards and actionable playbooks required for confident decision-making in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Non-Filtering Cloth Vacuum Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com